Global data center construction costs show upward trend
Global data center construction costs are increasing, driven by rising material and labor expenses, supply chain disruptions, and greater demand for advanced infrastructure. This trend affects project budgets worldwide.
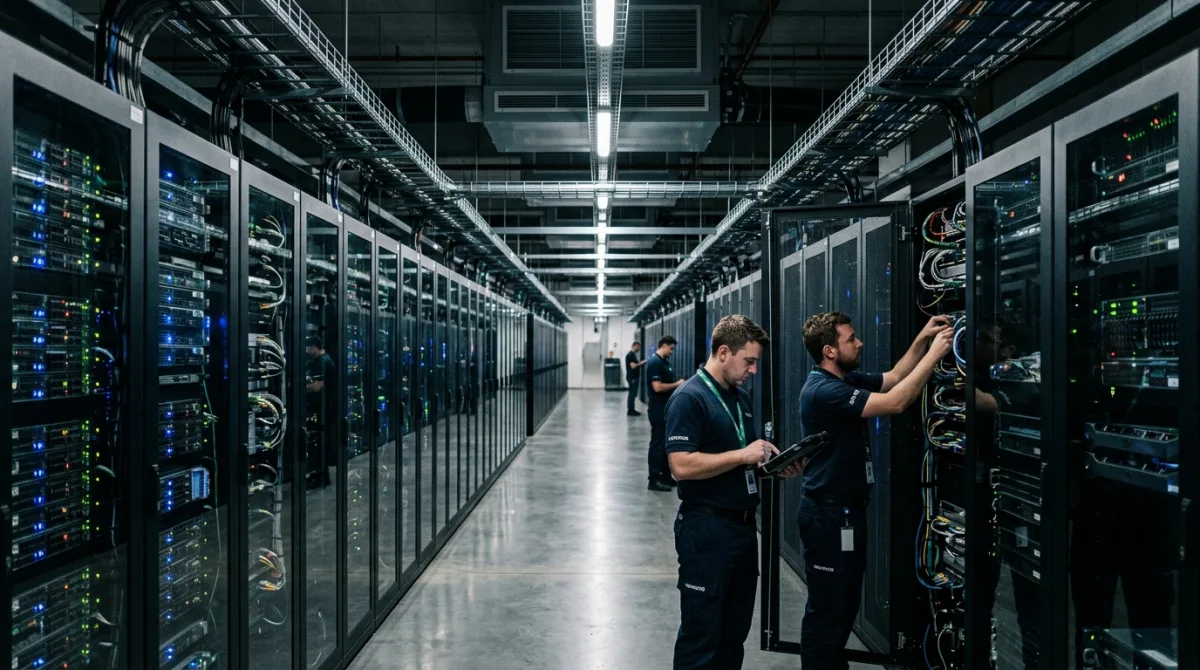
Global Data Centre Construction Costs Surge Amidst Demand
Global data centre construction costs have seen a sustained upward trend, with industry reports indicating a significant increase in capital expenditure required for new facilities across key markets. This escalation affects projects ranging from hyperscale campuses to smaller edge computing sites, impacting the overall economics of digital infrastructure development.
The observed rise represents a marked shift from previous periods of relative stability, reflecting a confluence of macroeconomic pressures and specific industry dynamics. Analysts project that this trend will continue in the short to medium term, influencing investment decisions and the strategic deployment of computing capacity worldwide.
Tracing the Origins of Escalating Expenses
The current upward trajectory in data centre construction costs began to manifest distinctly following global disruptions that exposed fragilities within complex supply chains. Initial pressures emerged from the immediate aftermath of the pandemic, which saw factory closures and logistics bottlenecks severely constrain the availability of essential building materials and specialised equipment.
This was compounded by an unprecedented surge in demand for digital services, accelerating the need for new data centre capacity. Cloud adoption, remote work, and increased streaming services fuelled a rapid expansion phase, creating a competitive environment for resources. As a result, lead times for critical components, such as power distribution units, cooling systems, and networking hardware, extended significantly, often stretching from a few months to over a year, simultaneously driving up procurement prices.
Further exacerbating the situation has been the volatility in global energy markets, directly impacting the cost of manufacturing and transporting materials. Alongside this, a growing shortage of skilled labour, including specialist engineers, construction project managers, and technicians proficient in complex data centre builds, has pushed up labour costs. These factors, acting in concert, have created a compounding effect on project budgets, leading to the substantial cost increases now widely reported across the sector.
Key Factors Shaping Data Centre Development
The financial viability and strategic placement of new data centre infrastructure are increasingly determined by a specific set of intertwined factors, each presenting its own trade-offs and challenges.
- Site selection: Access to large, stable power grids and high-capacity fibre optic networks is paramount, yet prime locations near urban centres or major internet exchange points are becoming scarce and prohibitively expensive. Constructing in more remote areas might lower land costs but introduces higher expenses for power transmission lines and robust network connectivity, alongside increased operational risks due to longer response times for maintenance.
- Supply chain resilience: Dependence on a limited number of specialised global manufacturers for critical, high-value components, particularly advanced processors, power infrastructure like uninterruptible power supplies (UPS), and cooling units, creates vulnerability. Diversifying suppliers can mitigate risk but often comes with increased complexity, potentially higher unit costs due to smaller order volumes with individual vendors, and longer qualification periods for new parts and partners, delaying project timelines.
- Energy requirements: Data centres are substantial consumers of electricity, and securing sufficient, reliable power, increasingly from renewable sources, is a significant cost driver. Integrating renewable energy solutions, such as dedicated solar farms or long-term power purchase agreements, can require substantial upfront investment or higher ongoing tariffs, even as grid reliability remains a primary concern, often necessitating expensive backup generation systems.
- Talent acquisition: A global shortage of highly skilled professionals across various disciplines—from mechanical and electrical engineers specialising in critical systems to civil engineers experienced in large-scale infrastructure projects—is driving up remuneration packages. While attracting top talent is crucial for efficient and safe construction, these elevated labour costs directly translate into higher overall project budgets, forcing companies to weigh immediate expenditure against long-term operational excellence.
These factors collectively present a complex landscape for developers, requiring careful strategic planning to balance immediate cost pressures against long-term operational efficiency and future scalability.
Impact on Cloud Service Providers and End-Users
Cloud Service Providers
The rising construction costs are directly impacting hyperscale cloud service providers, including major players like Amazon Web Services, Microsoft Azure, and Google Cloud, who are in a continuous cycle of expanding their global infrastructure. These companies invest tens of billions of pounds annually in new data centre builds and expansions; a percentage increase in construction costs translates into substantial additional capital outlay, potentially influencing their long-term financial forecasts and investment strategies.
This pressure can lead to revised capital expenditure budgets, potentially slowing the pace of new region deployments or driving a focus on optimising existing infrastructure more intensively. The scale of their operations means that even marginal cost increases per square foot or per megawatt can accumulate into significant figures, affecting return on investment calculations over the typical operational lifespan of a data centre, which can span 15 to 20 years.
The Mitigation of Technological Advancement
While the overall trajectory for data centre construction costs appears to be upward, a strong counter-argument suggests that technological advancements and increased operational efficiencies may, in part, mitigate the long-term financial burden. Innovations in cooling technologies, such as liquid immersion and advanced airflow management, alongside the development of more power-dense computing hardware, can significantly reduce the operational energy consumption per unit of compute capacity over time.
The overall cost trajectory for data centres is not solely defined by construction expenses, as ongoing operational efficiencies and technological advancements can significantly alter long-term financial projections.
Furthermore, the increased adoption of modular and pre-fabricated data centre components can streamline the construction process, potentially reducing labour costs and accelerating deployment times. These methods allow for greater standardisation and off-site assembly, leading to more predictable costs and fewer on-site complexities. Investment in automation within data centre operations also promises to reduce reliance on human intervention, leading to lower ongoing labour expenses and improved facility management, thereby offsetting some of the initial build cost increases.
The Long-term Impact on Global Digital Infrastructure Distribution
Uncertainty Regarding Geographical Spread
A significant open question remains regarding how these sustained increases in data centre construction costs will ultimately influence the geographical distribution of global digital infrastructure. It is not yet clear whether the economic pressures will lead to a consolidation of new builds in established, high-demand hubs, where existing infrastructure and connectivity might offer some cost efficiencies, or if it will compel developers to explore new, potentially less ideal, locations with lower land and labour costs, despite added logistical challenges.
The implications for digital sovereignty initiatives, which advocate for data to be stored and processed within national borders, are also uncertain. Higher costs could make it more challenging for smaller nations or regions to build out their own comprehensive data centre ecosystems, potentially reinforcing reliance on larger, more established global providers. The balance between cost-effectiveness, regulatory compliance, and regional data residency requirements is an evolving and complex area.
Observable Signals for Future Development
Moving forward, observable signals will provide insights into how the industry adapts to these escalating costs. One key indicator will be continued and intensified investment by major data centre operators and cloud providers into diversifying their supply chains, seeking out new component manufacturers and regional production capabilities to reduce single points of failure and negotiate better terms. This could manifest in strategic partnerships or even direct investments in manufacturing facilities.
Additionally, shifts in data centre design towards greater standardisation, pre-fabrication, and highly efficient modular deployment methods will likely become more prevalent, aiming to streamline construction and reduce on-site labour. Regulatory responses to the energy consumption and environmental impact of data centres, particularly in Europe, will also shape future specifications, potentially driving further innovation in sustainable design but also adding new compliance costs. Finally, the market may see further consolidation among smaller data centre operators who struggle with increased capital demands, or the emergence of new financing models designed to fund these increasingly expensive infrastructure projects.
Reader responses
Responses are read by the desk before they appear. A factual correction reaches us fastest here, and is made on the article itself with a dated note.
No responses on this report yet.