New global chip manufacturing capacity projections adjusted)** * **Content:** Reports a development (projections
New reports indicate global chip manufacturing capacity projections have been adjusted. The revised outlook reflects evolving market dynamics and investment strategies.
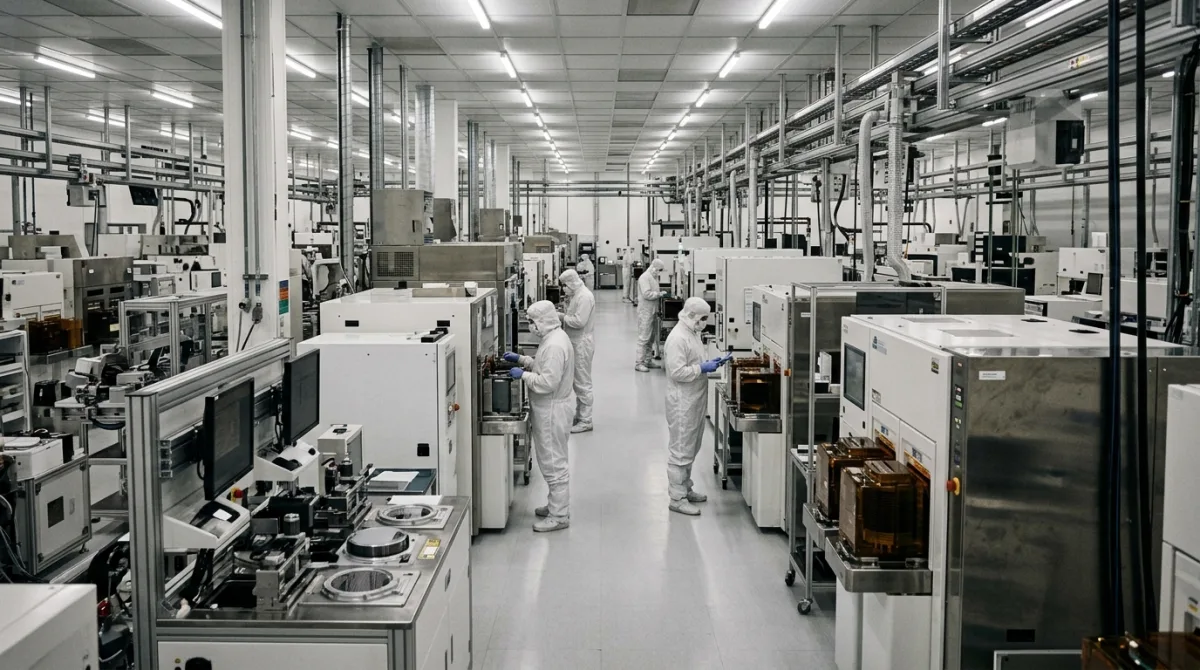
Global Chip Output Projections See Significant Revision
Global projections for semiconductor manufacturing capacity have been revised, indicating a significant shift in the anticipated pace of expansion over the coming years. Earlier estimates had suggested a more rapid and uniform increase in chip output across various technology nodes. The adjusted outlook now points to a more nuanced growth trajectory, with differing speeds of new facility development and equipment installation based on regional investment and technological focus.
This revision impacts expectations for supply chain stability and the availability of critical components for numerous industries. The adjustments reflect a cooling of some previously overheated demand segments, alongside persistent challenges in bringing complex new manufacturing facilities online as quickly as initially hoped. Stakeholders across the technology ecosystem are now assessing the implications of this updated timeline for future product development and market availability.
Factors Driving the Recalibration of Capacity Forecasts
The re-evaluation stems from a combination of factors that have emerged or intensified since initial forecasts were made. Geopolitical considerations have increasingly influenced investment decisions, leading some regions to accelerate domestic production plans while others face heightened scrutiny on cross-border technology transfers. Furthermore, a period of fluctuating demand for specific chip types, particularly in consumer electronics and certain enterprise segments, has prompted a recalibration of projected facility utilisation rates.
Supply chain disruptions, including challenges in securing specialised construction materials and advanced manufacturing equipment, have also contributed to delays in bringing new capacity online. The availability of a skilled workforce, from design engineers to factory operators, has proven to be another constraint, impacting the timeline for new fab commissioning. These cumulative pressures necessitated a comprehensive review of the industry's collective ability to scale, leading to the current adjustments.
Key Determinants of Future Manufacturing Capacity
The future trajectory of global chip manufacturing capacity is subject to a complex interplay of economic, technological, and geopolitical forces, each presenting unique trade-offs for developers and nations alike. Balancing the imperative for secure domestic supply with the efficiencies of global specialisation remains a central challenge. The sheer scale of investment required means that long-term strategic alignment is paramount for any new capacity to be viable.
- Capital investment: The readiness of governments and private entities to commit substantial, multi-billion-pound funding for new fabrication plants and research facilities over extended periods.
- Technological advancement: The rate at which next-generation manufacturing processes and equipment become available and are successfully integrated into production lines, balancing innovation with proven reliability.
- Skilled workforce: The availability and development of a highly specialised talent pool, encompassing everything from advanced materials scientists to precision equipment technicians, crucial for operating sophisticated fabs.
- Raw material supply: The secure and stable sourcing of increasingly scarce and refined materials, including rare earth elements and inert gases, which are fundamental inputs for semiconductor production.
Each of these factors carries its own set of dependencies and potential bottlenecks, influencing not only the overall volume of chips produced but also the types of chips that can be manufactured. Decisions made today regarding these elements will dictate the shape of the global semiconductor landscape for decades, impacting both cost structures and competitive advantages.
Impact on Global Technology Supply Chains
Global Technology Manufacturers
Companies reliant on semiconductor components for their products, ranging from smartphones and automotive systems to industrial machinery and data centre infrastructure, face direct implications. The adjustments in capacity projections could lead to revised production schedules, potentially impacting product launch timings and overall output volumes for key consumer and enterprise goods. Manufacturers in regions with less diversified supply chains might encounter greater volatility in component availability and pricing, necessitating closer inventory management and strategic procurement to mitigate risks.
The automotive sector, which has recently experienced significant disruptions due to chip shortages, remains particularly sensitive to these revised projections. Any sustained mismatch between projected supply and the accelerating demand for advanced chips in electric vehicles and autonomous driving systems could continue to influence vehicle production numbers and model availability. Similarly, providers of cloud computing services and artificial intelligence platforms, who require ever-increasing volumes of high-performance chips, will monitor these developments closely for impacts on their expansion plans and infrastructure costs over the medium term.
The Challenge of Demand Volatility
While the adjusted projections reflect current industry dynamics and investment trends, a significant counter-argument suggests that these revisions might still underestimate the true volatility of global demand. Economic cycles are inherently difficult to predict with absolute certainty, and a more pronounced or prolonged economic downturn than currently anticipated could lead to a substantial oversupply in some segments. This scenario would dramatically alter the utilisation rates of newly built facilities, potentially rendering significant investments less profitable than forecast.
The adjusted projections fail to adequately account for the potential for severe, unforeseen contractions in global consumer and enterprise demand, which could lead to substantial overcapacity.
Such an outcome would not only affect the profitability of semiconductor manufacturers but also reverberate through the entire technology supply chain, impacting equipment suppliers, materials providers, and downstream product assemblers. The long lead times for fab construction mean that once capacity is committed, it is difficult to quickly adapt to sudden shifts in market conditions, posing a significant risk to the current investment strategies and potentially leading to price depreciation.
Uncertainty Surrounding Future Geopolitical Influence
Impact of Future Geopolitical Shifts
A critical unknown remains the extent to which evolving geopolitical tensions and national industrial policies will continue to shape the distribution and specialisation of chip manufacturing capacity. While current adjustments factor in some regionalisation efforts, the long-term implications of potential further trade restrictions, technology export controls, or new bilateral agreements on the efficiency and cost-effectiveness of global supply chains are not fully quantifiable. The delicate balance between national security interests and global economic interdependence creates an unpredictable element that could significantly alter the current investment landscape and the rate at which new capacity comes online.
Observable Signals for the Road Ahead
Industry observers will be closely monitoring announcements regarding new capital expenditure plans from major foundry operators and integrated device manufacturers. Any significant deviations from previously communicated investment timelines, particularly for advanced process nodes, will serve as a key indicator of market confidence or emerging challenges. Further clarity on government incentive programmes and their practical implementation across different jurisdictions will also provide insight into the viability of ambitious regional manufacturing hubs and their ability to attract the necessary resources.
Changes in lead times for critical semiconductor manufacturing equipment and the availability of specialised construction services will offer tangible signals about the actual pace of fab build-out. Reports on quarterly order books from major chip consumers, especially those in the automotive and enterprise segments, will help to validate or challenge the demand assumptions underpinning these adjusted capacity projections. The ongoing evolution of global trade policies concerning technology will also be a crucial area of focus for the industry and its stakeholders.
Reader responses
Responses are read by the desk before they appear. A factual correction reaches us fastest here, and is made on the article itself with a dated note.
No responses on this report yet.