New regulations increase chip production overhead
New government regulations are projected to significantly increase the operational costs associated with semiconductor manufacturing, impacting supply chains and potentially consumer prices.
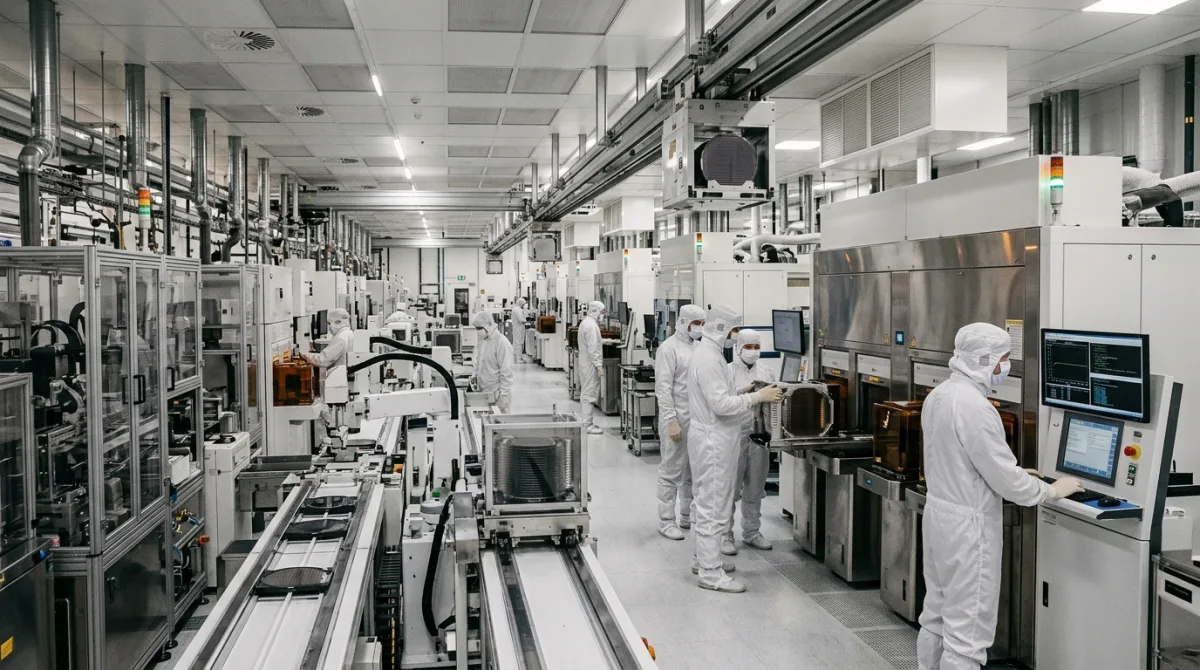
New Compliance Burdens Reshape Semiconductor Manufacturing Landscape
Semiconductor fabrication facilities globally are facing significantly increased operating costs following the implementation of new regulatory frameworks designed to enhance supply chain resilience and security. These comprehensive mandates introduce a range of revised operational protocols and reporting requirements, directly impacting the financial overhead of producing integrated circuits.
The changes stem from a coordinated effort by several major economic blocs to mitigate future disruptions in a sector critical to modern infrastructure and consumer goods. Manufacturers are now required to invest in updated processes, enhanced auditing procedures, and potentially new equipment to meet the stringent criteria.
Evolving Global Dynamics Prompt Policy Shift
The trajectory towards heightened regulation began several years prior, driven by a series of geopolitical events and widespread supply chain vulnerabilities that exposed critical dependencies in the technology sector. Initial discussions among policymakers focused on the strategic importance of domestic and allied chip production capabilities, aiming to reduce reliance on single points of failure.
These initial concerns evolved into a broader policy agenda encompassing not only security but also sustainability and ethical labour practices within the complex semiconductor ecosystem. Consultations with industry stakeholders and academic institutions informed the gradual development of the regulatory proposals, which sought to balance innovation with oversight.
The finalisation of these frameworks followed extensive legislative reviews and public commentary periods in various jurisdictions. The staggered but ultimately convergent implementation of these rules marks a significant shift from previous, less prescriptive approaches to governing the high-tech manufacturing industry.
This culminated in the enforcement of rules that mandate specific standards for materials sourcing, environmental impact, and data security protocols across the entire fabrication process. The accumulated effect of these individual requirements translates directly into the observed increase in operational expenditures for chip producers.
Key Factors Shaping Market Reaction
The ultimate impact of these new regulations will be determined by several interconnected factors, creating a complex array of trade-offs for the global semiconductor market.
- Technology adoption: The speed at which manufacturers can integrate new, compliant fabrication technologies and processes will directly influence their ability to absorb costs and maintain competitive pricing.
- Global demand: Sustained robust demand for semiconductors across diverse sectors may allow producers to pass on a larger share of increased costs to customers without significantly affecting sales volumes.
- Government incentives: The availability and scope of government subsidies or tax credits aimed at offsetting compliance costs in specific regions could skew competitive advantages and investment decisions.
- Industry consolidation: The financial burden may disproportionately affect smaller manufacturers, potentially accelerating industry consolidation as larger firms with greater capital reserves adapt more readily.
These elements will interact to define the market's equilibrium, influencing everything from investment in research and development to the final price points of electronic devices. The balance between regulatory pressure and market forces will be continuously recalibrated.
Wider Repercussions for Industry and Consumers
Chip Manufacturers
The primary group affected by the new regulations is the global cohort of semiconductor manufacturers, particularly those operating advanced fabrication plants. Companies are now faced with substantial capital expenditure for upgrading facilities to meet new environmental standards, alongside increased operational expenditure for enhanced supply chain auditing and security protocols.
Large-scale producers with diverse manufacturing footprints may be better positioned to absorb these costs due to economies of scale and existing compliance infrastructure, though their global operations still require significant re-evaluation. Smaller, specialised foundries, however, could face a more acute challenge, potentially impacting their ability to compete and innovate without substantial external investment.
Downstream Industries
Industries heavily reliant on a steady and affordable supply of semiconductors, such as automotive, consumer electronics, and data centres, are also directly affected. They anticipate increased component costs, which could lead to upward price revisions for finished products or pressure on profit margins if the costs cannot be fully passed on to end-users.
The automotive sector, for instance, which was particularly vulnerable to chip shortages in recent years, could see further delays in new vehicle production or higher retail prices for models incorporating advanced electronic features. Manufacturers in these sectors are now reviewing their procurement strategies and exploring options for diversifying their component supply chains.
Consumers
Ultimately, a substantial portion of the increased production overhead is projected to filter down to consumers through higher prices for electronic devices and products that incorporate advanced semiconductors. This encompasses a broad range of items, from smartphones and laptops to home appliances and electric vehicles.
While the immediate impact on individual product prices might appear incremental, the cumulative effect across multiple purchases could represent a noticeable increase in household technology expenditure over the next several years. The timing and magnitude of these price adjustments will vary depending on market competitiveness and consumer demand elasticity.
Concerns Over Economic Impact and Innovation
While proponents argue the regulations are necessary for long-term security and stability, a significant body of industry analysis raises concerns about their potential to stifle innovation and increase consumer prices without achieving the desired level of supply chain independence. Critics contend that the broad scope of the mandates creates an undue burden that could inadvertently disadvantage regions implementing them.
The current regulatory approach risks making domestic chip production economically unviable, potentially driving investment and innovation to less-regulated markets.
This perspective suggests that the added compliance costs could deter investment in cutting-edge research and development within regulated jurisdictions, shifting the focus towards meeting compliance rather than pioneering new technologies. The argument posits that an overemphasis on security at the expense of economic agility could weaken the very industry it seeks to protect.
Uncertainty Surrounding Long-Term Market Structures
How Far Will Prices Rise?
The precise extent to which these increased production overheads will translate into higher end-user prices remains a significant unknown. Market dynamics, including global demand fluctuations, competitive pressures among chip manufacturers, and the willingness of downstream industries to absorb costs, will play a critical role in determining the final pricing structure. Economic models offer various projections, but the real-world pass-through rate will depend on the nuanced interplay of these factors over the coming quarters and years, making accurate long-term forecasts challenging to produce.
Observable Signals for Future Trajectory
Market observers will be closely monitoring several key indicators to gauge the evolving impact of the new regulations. Forthcoming quarterly earnings reports from major semiconductor manufacturers will offer initial insights into the financial performance under the revised cost structures, detailing capital expenditure increases and any shifts in profit margins.
Further signals will emerge from investment announcements by these firms, particularly regarding new fabrication plant construction or expansion projects, which could indicate a strategic response to the regulatory environment. Changes in the geographical distribution of new investment, favouring regions with specific incentive programmes, will also be closely watched as an indicator of long-term shifts in the global manufacturing footprint.
Reader responses
Responses are read by the desk before they appear. A factual correction reaches us fastest here, and is made on the article itself with a dated note.
No responses on this report yet.