Semiconductor supply chain sees shifting inventory levels
The semiconductor supply chain is experiencing a significant shift in inventory levels. After periods of scarcity, a build-up of stock is now observed, indicating a recalibration of supply and demand dynamics.
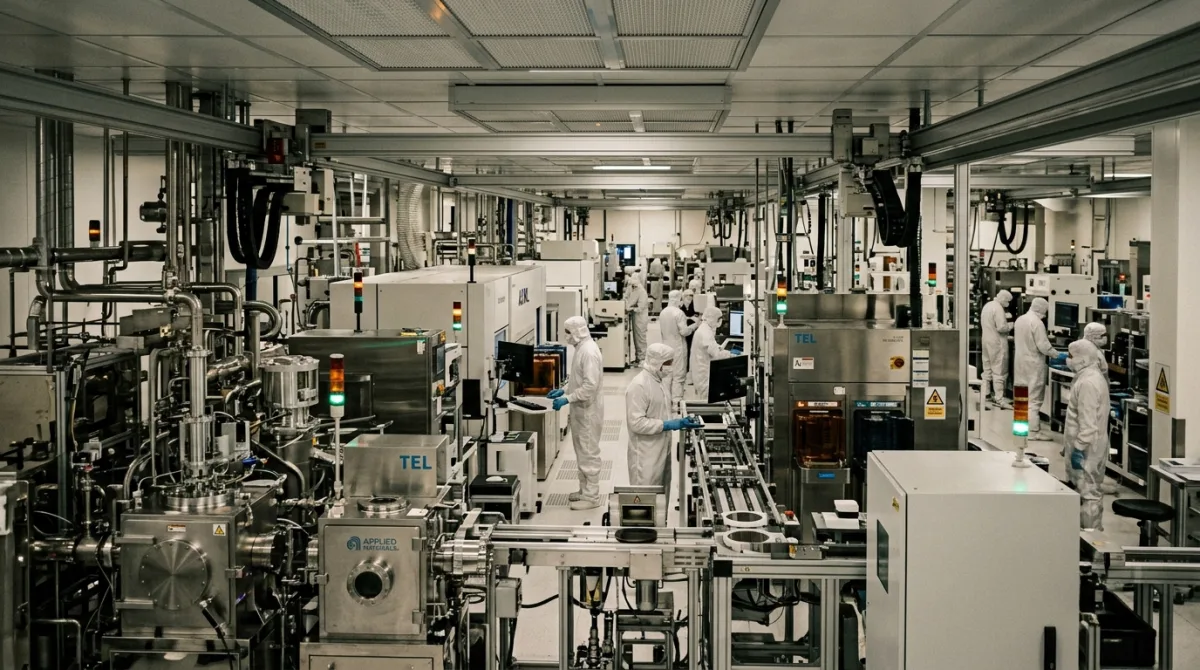
Semiconductor Inventory Levels Undergo Complex Rebalancing
The global semiconductor supply chain is currently experiencing a recalibration of inventory levels, moving away from the acute shortages of recent years towards a more complex landscape of mixed surpluses and deficits across different chip types. This shift marks a significant adjustment for manufacturers, distributors, and end-users of electronic components worldwide.
Rather than a uniform oversupply or shortage, the market now presents a bifurcated picture where demand for some advanced chips remains robust, while more mature or commoditised components face excess stock. This differentiation underscores a dynamic period for the foundational industry.
Tracing the Path to Present Inventory Adjustments
The sequence leading to these varied inventory levels began with the unprecedented surge in demand for electronics, triggered by widespread remote work and schooling during the pandemic. This created an intense period of chip scarcity across numerous sectors, from consumer electronics to automotive manufacturing.
In response to prolonged lead times and the imperative to maintain production, many original equipment manufacturers (OEMs) resorted to placing multiple, overlapping orders with various foundries and suppliers, a practice often termed "double ordering." This strategy was intended to secure necessary components and safeguard against further supply disruptions.
As initial supply constraints gradually eased and global macroeconomic conditions began to tighten, consumer demand for certain electronics, particularly personal computers and smartphones, started to moderate more rapidly than anticipated. This confluence of improved manufacturing capacity, the unwinding of over-orders, and a slowdown in end-market consumption contributed directly to a build-up of excess inventory for specific types of integrated circuits.
Conversely, advanced chips vital for emerging technologies such as artificial intelligence, high-performance computing, and certain data centre applications continued to face persistent, high demand. This persistent demand, coupled with the extended fabrication times for these cutting-edge components, has created a distinct shortage in this segment, contrasting sharply with the surplus observed elsewhere.
Factors Shaping the Future of Chip Stockpiles
The future trajectory of semiconductor inventory levels is subject to several interconnected factors, each carrying its own trade-offs and potential for market impact. Understanding these elements is crucial for anticipating market movements.
- Macroeconomic stability: Global economic growth rates directly influence consumer and enterprise spending on electronic devices, dictating the underlying demand for chips. A downturn could exacerbate existing inventory gluts, while a rebound could quickly absorb surpluses, creating a trade-off between market stability and rapid demand shifts.
- Capacity utilisation: The operational efficiency and output levels of semiconductor fabrication plants (fabs) determine the pace at which new chips enter the supply chain. Low utilisation can signal oversupply or reduced demand, leading to production cuts, while consistently high utilisation suggests robust demand or persistent bottlenecks, balancing output against market absorption.
- Technological innovation cycles: The introduction of new product generations, such as advanced AI processors or next-generation memory, can rapidly shift demand away from older, less capable components, potentially creating obsolescence risks for existing inventory. This creates a trade-off between managing current stock and investing in future readiness.
- Geopolitical trade policies: Restrictions on technology exports, tariffs, or subsidies enacted by major economic blocs directly impact the flow of components, equipment, and raw materials across borders. Such policies can disrupt established supply routes, force regionalisation of manufacturing, and alter the competitive landscape for chip producers and consumers, balancing national security with global efficiency.
These elements collectively shape the complex dynamics of the semiconductor market, influencing pricing, lead times, and the strategic decisions of companies at every stage. Their interplay will determine the speed and nature of the inventory rebalancing.
Impacts Across the Technology Ecosystem
Chip Manufacturers and Foundries
Major semiconductor manufacturers and contract foundries are experiencing a direct impact on their order books and revenue projections. Companies focused on mature process nodes, which produce less advanced chips for automotive and industrial applications, have reported declining utilisation rates in some facilities, leading to pressures on profitability over the past quarters.
This sector previously benefited from sustained high demand during the acute shortages, but now faces the challenge of rebalancing production with current market absorption and managing existing stock. Conversely, foundries specialising in advanced nodes continue to see strong demand, maintaining high capacity utilisation.
Original Equipment Manufacturers (OEMs)
OEMs, ranging from smartphone makers to automotive giants, are navigating a mixed bag of component availability. While some standard components are now more readily available, reducing previous production delays, acquiring cutting-edge chips for new product development remains competitive and can still lead to extended lead times.
Companies are adjusting their purchasing strategies, moving from aggressive over-ordering to more measured, "just-in-time" approaches, albeit with caution given past disruptions. This shift affects their production schedules, inventory holding costs, and ultimately their profit margins over the coming quarters, as they adapt to the fluctuating supply environment.
Technology Consumers
For consumers in the UK, the shifting inventory levels translate into varied product availability and pricing. A broader range of mid-tier electronic devices, such as mainstream laptops and white goods, may become more accessible and potentially see price stabilisation or modest reductions due to increased component availability.
However, the cost of high-end gadgets, particularly those leveraging the latest AI-enabled processors or next-generation graphics cards, may remain elevated due to persistent demand for these advanced components and limited supply. This creates a divergence in the affordability and choice of technology products available in the market, with premium items remaining a considerable investment.
Scrutinising the Inventory Narrative
While the prevailing narrative suggests that shifting inventory levels indicate a movement towards market equilibrium, some industry observers argue that this account may oversimplify the underlying structural challenges within the semiconductor supply chain. They contend that the current recalibration is primarily a cyclical downturn, exacerbated by broader macroeconomic factors, rather than a fundamental resolution of systemic vulnerabilities that persist.
The current inventory adjustments are a superficial market correction, masking persistent geographical concentration of manufacturing and critical intellectual property that leaves the global supply chain inherently fragile against future disruptions.
This perspective highlights that despite short-term availability improvements for certain chip types, the reliance on a limited number of advanced fabrication sites, often concentrated in geopolitically sensitive regions, continues to pose a significant long-term risk. Without substantial diversification of manufacturing capabilities across different continents, the system's susceptibility to shocks from natural disasters, trade disputes, or regional conflicts will persist, irrespective of current stock levels or temporary market corrections.
Unanswered Questions Regarding Market Stability
The Pace of Demand Recovery
A central unknown revolves around the trajectory and strength of a sustained recovery in global demand for semiconductors. While some industrial and automotive sectors show signs of stabilisation, the overall economic outlook remains uncertain, influenced by inflation, interest rates, and geopolitical tensions across major economies. It is unclear whether the demand for consumer electronics will rebound robustly enough to absorb existing inventories without significant price reductions, or if industrial and automotive sectors will sustain their projected growth to drive new orders at pre-pandemic levels. The rate at which new applications, such as pervasive artificial intelligence, translate into widespread chip demand also remains to be fully quantified, making it difficult to project the long-term demand-supply balance beyond the immediate horizon.
Observable Signals for Future Supply Chain Direction
Industry participants will be closely monitoring several key indicators to gauge the ongoing stability and direction of the semiconductor supply chain. Observing the order-to-bill ratios reported by major foundries will provide early signals of demand trends, indicating whether new orders are outstripping or falling behind shipments. Any significant shifts in lead times for critical components, especially those for high-performance computing and artificial intelligence, will also offer immediate insight into underlying supply constraints or easing pressures.
Furthermore, the financial reports and earnings calls from both chip manufacturers and their primary customers, the OEMs, will offer granular data on inventory write-downs, capital expenditure plans, and revenue guidance. These disclosures will reflect how companies are adapting their production and purchasing strategies in response to the evolving market conditions, providing concrete evidence of whether the inventory recalibration is progressing towards a more balanced and predictable supply environment, or if further volatility should be anticipated.
Reader responses
Responses are read by the desk before they appear. A factual correction reaches us fastest here, and is made on the article itself with a dated note.
No responses on this report yet.