Chip manufacturing faces tighter environmental compliance costs
Chip manufacturers are experiencing increased operational costs due to more stringent environmental regulations. This development is prompting a reevaluation of production processes and waste management strategies.
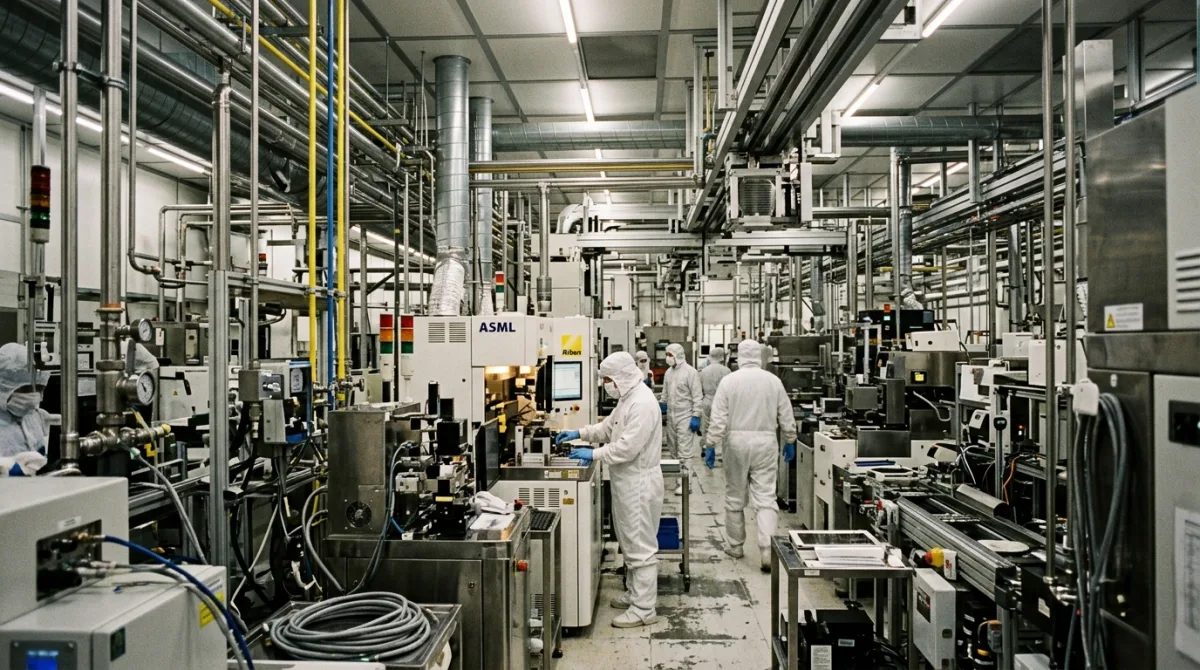
Chip Manufacturing Faces Elevated Environmental Compliance Burdens
Global semiconductor manufacturers are confronting significantly elevated operational costs as a direct result of a concerted regulatory push for tighter environmental compliance across their fabrication facilities. This development signals a fundamental shift in how chip production, historically intensive in resource consumption and waste generation, will be governed and financed moving forward. The financial burden is projected to impact both the ongoing running of existing fabs and the design and construction of new facilities, altering long-term investment strategies.
The industry's ambitious capacity expansion plans, already substantial with billions being committed to new foundries worldwide, will now need to factor in these additional environmental outlays. Such costs encompass everything from advanced waste treatment systems to more efficient energy consumption protocols and enhanced water recycling infrastructure. This regulatory tightening is expected to ripple through the entire supply chain, potentially influencing the final cost of electronic devices.
Tracing the Path to Stricter Environmental Oversight
The current trajectory towards enhanced environmental accountability in chip manufacturing follows years of escalating global concern over industrial ecological footprints. Initial impetus stemmed from international agreements aiming to curb greenhouse gas emissions, subsequently translating into national and regional legislative frameworks targeting energy-intensive sectors like semiconductor production. These frameworks mandate a reduction in various pollutants and a more sustainable approach to resource management.
Specific attention has increasingly focused on the semiconductor industry's unique environmental challenges, including its substantial water demands, high energy consumption for cleanroom operations, and the generation of persistent perfluorinated compounds (PFCs) and other hazardous waste streams. Scientific reports detailing the long-term impact of these industrial by-products have amplified calls for more stringent oversight from environmental agencies and public bodies. This has prompted policymakers to revise existing environmental permits and introduce new mandates for waste reduction, water recycling, and advanced emissions abatement technologies, thereby increasing compliance complexity and cost.
Influential Factors Shaping the Compliance Landscape
The ultimate impact of these tighter environmental compliance costs will be determined by a complex interplay of technological, geographical, and market-driven factors. Navigating these elements will require strategic decisions from manufacturers, affecting everything from research and development budgets to facility location choices and pricing models. The industry's ability to adapt swiftly to these evolving demands will be critical.
- Technological Readiness: The current availability and efficacy of advanced filtration systems for chemical by-products, along with highly efficient water recycling and energy recovery systems, will dictate the immediate financial outlay. The trade-off lies in deploying established, often costly, abatement solutions versus investing in developing and scaling up newer, potentially more cost-effective but unproven, green technologies.
- Geographic Regulatory Divergence: Environmental regulations vary significantly between major chip-producing regions suchs as East Asia, Europe, and North America, creating a patchwork of compliance requirements. This divergence presents a trade-off for companies deciding where to build new fabrication plants or expand existing ones, as jurisdictions with more stringent rules may incur higher initial and ongoing environmental costs but could also offer long-term stability in regulatory frameworks.
- Market Demand and Price Elasticity: The semiconductor market's responsiveness to potential price increases will largely determine manufacturers' ability to pass on compliance costs to end consumers. The trade-off involves absorbing a portion of the increased expenses, thereby risking reduced profit margins, versus raising chip prices and potentially impacting demand or competitive positioning in an already tight market.
- Supply Chain Integration: The extent to which major chip manufacturers can influence and enforce environmental compliance standards among their upstream suppliers of raw materials, chemicals, and equipment is crucial. This involves a trade-off between demanding stringent environmental practices from suppliers, which may increase their costs, and ensuring the continued resilience and availability of critical components within a complex global supply chain.
These factors collectively define the operational environment for chipmakers, influencing investment decisions, strategic partnerships, and research priorities. The balance between environmental responsibility and economic viability remains a central challenge for the sector.
Stakeholders Bearing the Brunt of Increased Costs
Semiconductor Manufacturers
Leading semiconductor foundries, responsible for a substantial share of global chip production, are directly affected by these escalating compliance costs. Companies operating multi-billion-pound fabrication plants, particularly those expanding capacity or building new facilities, face significant capital expenditure increases for environmental control systems and infrastructure upgrades. Estimates suggest that environmental compliance could add several percentage points to the overall cost of new fab construction, potentially reaching hundreds of millions of pounds for a single advanced facility over its operational lifespan of 20 years or more.
Smaller manufacturers and new market entrants, who often operate with tighter margins and less capital, may find the upfront investment and ongoing operational costs a substantial barrier to competitiveness or even market entry. This dynamic could inadvertently consolidate market power among the largest, most financially robust players, potentially reducing overall market diversity. The increased operational expenditure will also impact the profitability of existing fabs, requiring careful margin management and efficiency drives over successive fiscal quarters.
The Contention: Competitiveness Versus Environmental Imperative
While the drive for environmental sustainability is widely acknowledged, a prominent objection to rapidly escalating compliance costs centres on concerns about global competitiveness. Industry bodies and some policymakers have voiced apprehension that overly aggressive or unevenly enforced regulations could disadvantage manufacturers operating in regions with stricter standards. This could potentially lead to a scenario where production shifts to areas with less demanding environmental oversight, undermining the very goals of the regulations.
Critics argue that overly stringent or uncoordinated environmental regulations risk driving semiconductor manufacturing investment and job creation towards jurisdictions with less demanding environmental standards, ultimately failing to achieve global environmental benefits.
This argument highlights the capital-intensive nature of the semiconductor industry, where even slight cost differentials can influence decisions on where to site new facilities or expand existing operations. Companies invest billions of pounds over decades in their plants, making long-term regulatory stability and a level playing field critical considerations. The concern is that unilateral action by one region could inadvertently lead to 'carbon leakage' or 'environmental leakage', where emissions and pollution simply relocate rather than being reduced globally.
Uncertainties Regarding Long-Term Economic Repercussions
Impact on End-User Chip Pricing and Supply Chains
A significant unknown remains the precise long-term economic impact on end-user chip prices and, consequently, the broader technology supply chain. While manufacturers are facing direct cost increases, the extent to which these will be absorbed by profit margins or passed on to consumers is not yet clear, and will likely depend on factors such as market demand elasticity, competitive pressures, and the global economic climate. Furthermore, the cumulative effect of disparate regional environmental policies on global supply chain resilience is still being assessed; there is no consensus on whether these increased costs will primarily spur innovation in more sustainable manufacturing processes, or if they will act as a brake on necessary capacity expansion, potentially exacerbating future chip shortages for critical components in consumer electronics, automotive, and industrial sectors.
Observable Signals for the Road Ahead
Observers will be closely monitoring forthcoming corporate earnings reports from major semiconductor manufacturers for specific indications of increased capital expenditure allocated to environmental compliance and sustainability initiatives. These reports are expected to detail investments in new water treatment plants, advanced air filtration systems, and energy-efficient equipment, providing tangible evidence of the financial commitment. Any notable shifts in reported profit margins or guidance on future operational costs will also offer insights into the immediate financial pressures being experienced by the industry.
Statements from industry trade associations, such as the European Semiconductor Industry Association or the Semiconductor Industry Association, are also expected to provide insights into lobbying efforts aimed at standardising international environmental regulations or securing governmental support for green technology adoption through subsidies or tax incentives. Furthermore, the geographical distribution of new fabrication plant investments will serve as a key signal, revealing whether regulatory stringency in certain regions is influencing long-term strategic decisions regarding manufacturing location. Any shifts in reported water consumption, energy intensity per wafer produced, or waste generation metrics will offer tangible evidence of the effectiveness of these new compliance measures. The evolution of pricing strategies for various chip types will also bear watching for any direct correlation with rising production costs, providing a clearer picture of how these expenses are being managed across the value chain.
Reader responses
Responses are read by the desk before they appear. A factual correction reaches us fastest here, and is made on the article itself with a dated note.
No responses on this report yet.