Supply chain shifts alter global chip delivery timelines
Global chip delivery timelines are undergoing significant alterations as supply chain shifts reshape the industry. These changes affect manufacturing schedules and product availability worldwide.
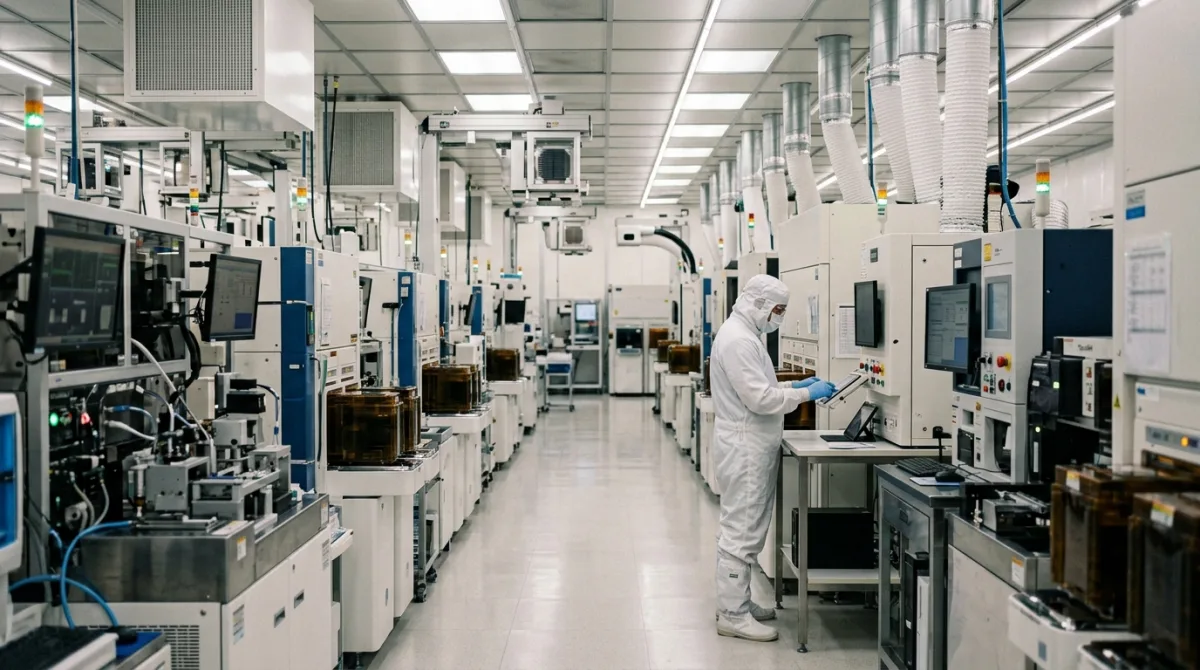
Global Chip Delivery Faces Reworked Schedules
Fundamental shifts in the global semiconductor supply chain are demonstrably altering delivery timelines for microchips across industries, impacting everything from consumer electronics to critical infrastructure. This reorientation is moving away from long-established manufacturing and logistics pathways, resulting in varying lead times for essential components.
The adjustments are not uniform, with some chip categories experiencing extended delays while others see diversified sourcing options emerge. These changes reflect a deliberate move by various actors to mitigate future disruptions and secure access to vital silicon, a cornerstone of modern technological output.
From Efficiency to Resilience: A Supply Chain Evolution
The current re-evaluation of chip delivery timelines follows a period dominated by optimised, lean supply chains that prioritised cost efficiency and just-in-time inventory. This model, while effective for decades, proved vulnerable during global events that triggered factory shutdowns and logistics bottlenecks. Initial disruptions highlighted a critical over-reliance on a limited number of manufacturing hubs for advanced chip production, particularly in East Asia.
Subsequent geopolitical tensions further accelerated calls for greater regionalisation and diversification of semiconductor fabrication. Governments in Europe, North America, and other regions initiated significant investment programmes aimed at boosting domestic chip manufacturing capabilities. These policy interventions, alongside private sector capital allocation, are now beginning to yield tangible, albeit nascent, changes in where and how chips are produced and subsequently distributed.
The cumulative effect of these strategic shifts, from immediate crisis response to long-term investment in new facilities, has been a gradual but persistent alteration of established delivery routes. The emphasis has visibly shifted from sheer speed and lowest cost to securing resilient, geographically diverse sources of supply, influencing procurement strategies and ultimately, delivery schedules.
Key Factors Shaping Future Deliveries
The trajectory of chip delivery timelines is being shaped by several interconnected factors, each presenting distinct trade-offs for manufacturers and consumers alike. Understanding these dynamics is central to comprehending the evolving landscape of semiconductor availability.
- Geopolitical stability: Ongoing international relations between major economic blocs directly influence trade policies, export controls, and the willingness of nations to engage in cross-border technology transfer. Instability can lead to fragmented supply routes, increasing complexity and potential delays.
- Manufacturing capacity: The commissioning of new fabrication plants, particularly in regions aiming for self-sufficiency, introduces alternative production sources. However, the multi-year construction and ramp-up phases mean immediate gains are limited, and initial costs for chips from these new facilities may be higher than from established hubs.
- Raw material access: The availability and secure sourcing of critical raw materials, such as rare earth elements and specific chemicals, are fundamental. Disruptions in the mining or processing of these materials, often concentrated in specific geographies, can cascade through the entire chip production process, regardless of fabrication location.
- Logistics infrastructure: The robustness of global shipping, air freight, and ground transportation networks plays a crucial role in moving finished chips from factories to end-users. Congestion at ports, labour shortages, or rising fuel costs can directly impact transit times and add to overall delivery expenses.
These factors often interact in complex ways, with improvements in one area potentially offsetting challenges in another. The balance between cost-effectiveness and supply resilience remains a central tension for businesses managing their semiconductor procurement.
Impact on Consumer Electronics and Automotive Sectors
Key Industries Grapple with New Realities
Manufacturers in the consumer electronics and automotive sectors are among the most significantly affected by these evolving delivery timelines. For consumer electronics, this means adjustments to product launch schedules and, in some instances, revised pricing structures to account for increased procurement and logistics costs. Companies that rely on a broad spectrum of chip types, from advanced processors to basic microcontrollers, must manage a complex web of new lead times.
The automotive industry, already having experienced substantial production halts due to chip shortages, is particularly sensitive to these shifts. Modern vehicles incorporate hundreds of semiconductors for everything from engine management to infotainment systems. Extended delivery timelines for even a few critical components can delay vehicle assembly for weeks or months, leading to reduced output and impact on new vehicle availability for consumers over a sustained period.
The Counter-Argument: Overstated Disruptions
While reports detail extensive shifts and their implications, some industry analysts contend that the narrative of widespread, permanent disruption to chip delivery timelines is overstated. They suggest that many of the current challenges are transient, representing a recalibration rather than a fundamental overhaul of global supply chains.
The current shifts in chip delivery timelines represent a temporary market correction and strategic inventory build-up rather than a lasting structural change to global semiconductor production and distribution.
This perspective posits that the market will naturally adjust as new fabrication plants come online and as companies refine their diversified sourcing strategies, eventually normalising delivery schedules. Proponents of this view suggest that the existing infrastructure, though tested, remains fundamentally robust and adaptable enough to absorb these changes without lasting, detrimental alterations to overall efficiency or speed.
Uncertainty Regarding Full Regionalisation Impact
The Long-Term Efficacy of Domestic Production
A central unanswered question revolves around the long-term efficacy and economic viability of the push towards greater regionalisation in semiconductor manufacturing. While new fabrication plants are being constructed in various nations, the true impact on global delivery timelines and overall chip costs remains to be fully observed.
It is not yet clear whether these new regional facilities will achieve the same economies of scale and technological sophistication as the established global leaders. The ability of these nascent hubs to sustain competitive pricing and consistent output without significant ongoing government subsidies is a key area of uncertainty. The full extent to which these investments will genuinely reduce geopolitical supply risks or simply redistribute them is also an open question that will shape future market dynamics.
Observable Signals for Future Trajectories
Observers will be watching for several key indicators to gauge the future trajectory of chip delivery timelines. Public announcements from major semiconductor manufacturers regarding the completion and operational status of new fabrication facilities, particularly those outside established hubs, will offer concrete evidence of capacity shifts. Furthermore, changes in inventory levels reported by large electronics and automotive companies will signal whether supply is beginning to meet demand more consistently.
Further, government policy shifts concerning trade agreements, export controls, and investment incentives for the semiconductor industry will provide insight into the geopolitical commitment to these new supply chain structures. Any sustained reduction in average lead times for specific chip categories, as reported by industry associations, would indicate a material improvement in overall delivery schedules, moving beyond the current period of re-evaluation and adjustment.
Reader responses
Responses are read by the desk before they appear. A factual correction reaches us fastest here, and is made on the article itself with a dated note.
No responses on this report yet.