Digital infrastructure expands under revised cost models
The expansion of digital infrastructure is progressing under revised cost models, indicating a strategic shift in funding and implementation approaches for technological development.
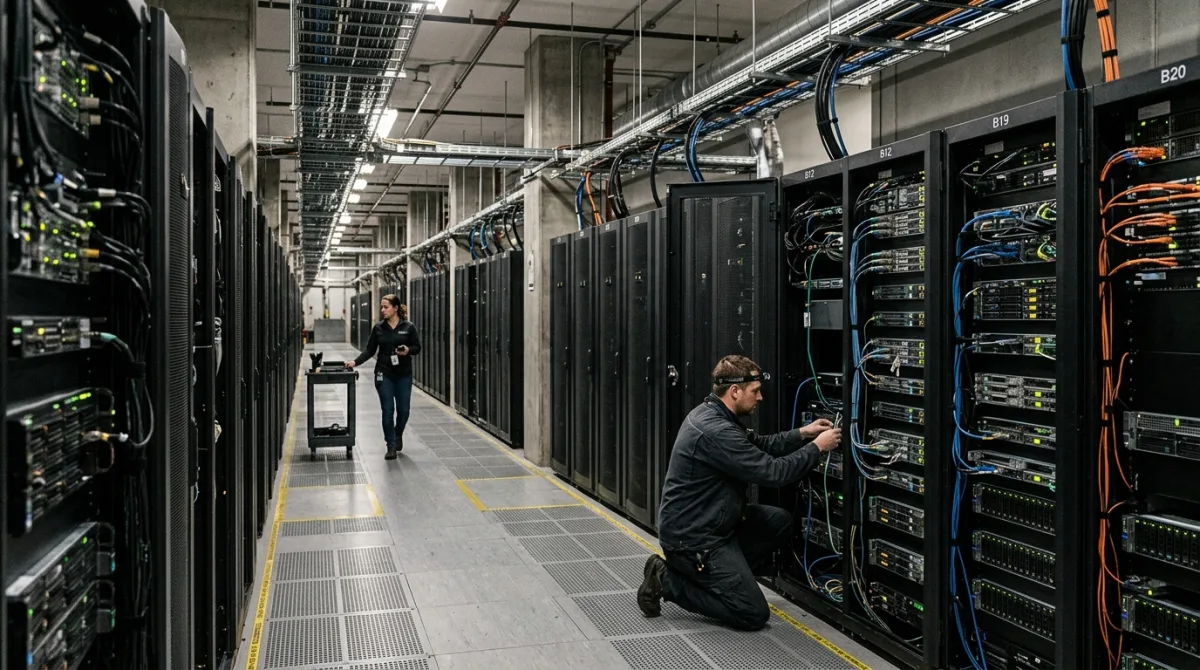
New Funding Fuels Network Expansion
Digital infrastructure across the United Kingdom is undergoing significant expansion, driven by widespread adoption of revised cost models for network deployment and data centre operations. This shift involves a move away from traditional, heavy upfront capital expenditure (CapEx) towards more flexible operating expenditure (OpEx) frameworks and innovative financing structures.
These new models encompass a range of approaches, including build-operate-transfer agreements, lease-to-own arrangements for hardware, and shared network infrastructure initiatives. The aim is to distribute investment costs over longer periods and align expenses more closely with operational revenues, making large-scale projects more financially viable for a broader array of providers.
Evolution of Investment Strategies
The progression to these revised cost models has been a gradual but deliberate sequence, emerging from several converging pressures and opportunities within the technology sector. Historically, digital infrastructure projects, particularly in fibre-optic broadband and large-scale data centres, were characterised by immense initial investment requirements and protracted periods to achieve a return on capital.
This traditional funding model often limited the pace and scope of infrastructure rollout, especially in less densely populated or economically challenging areas. Over the past decade, however, several factors began to alter this landscape. Technological advancements, such as more efficient fibre deployment techniques, pre-fabricated modular data centre components, and advances in wireless transmission, started to reduce the per-unit cost of infrastructure components and accelerate deployment times.
Simultaneously, the broader tech industry witnessed a profound shift towards 'as-a-service' models, demonstrating the commercial viability and appeal of subscription-based consumption for everything from software to cloud computing. This proved that predictable, recurring revenue streams could attract a different class of investor, less focused on immediate capital recovery and more on long-term, stable returns.
Institutional investors, including pension funds and infrastructure-focused private equity firms, increasingly sought stable, long-term assets with predictable cash flows, finding digital infrastructure an attractive proposition when structured appropriately. Regulatory bodies and governments, recognising the economic and social imperative for ubiquitous high-speed connectivity, also began to introduce policy incentives and funding programmes designed to de-risk investment and encourage alternative financing approaches. The accelerated demand for robust digital connectivity during recent global events further underscored the urgency for more agile and sustainable investment paradigms.
Key Drivers of Project Success
The successful expansion of digital infrastructure under these new cost models hinges on several critical factors, balancing potential benefits against inherent risks.
- Capital Access: The consistent availability of long-term, patient capital from institutional investors and specialised funds is crucial, as these models often prioritise predictable, smaller returns over extended durations.
- Regulatory Certainty: A stable and predictable regulatory environment regarding planning permissions, spectrum allocation, and wholesale access pricing significantly de-risks large-scale infrastructure investments, encouraging participation from private capital.
- Technological Readiness: Continued advancements in cost-effective and reliable hardware for network deployment, data processing, and energy management are essential to maintain the economic viability of projects over their lifecycle.
- Market Demand: Sustained and growing demand for high-bandwidth connectivity and digital services from both residential and business customers is fundamental to generating the consistent revenue streams these OpEx-heavy models rely upon.
These factors collectively determine the pace and reach of digital infrastructure development, influencing decisions from major network operators to smaller regional providers. Their interplay shapes the long-term investment landscape and the ultimate cost structures for consumers and businesses alike.
Impact on Providers and Communities
Internet Service Providers and Underserved Regions
The shift to revised cost models is significantly affecting internet service providers (ISPs), enabling them to undertake network deployments that were previously financially prohibitive. By converting a substantial portion of upfront capital expenditure into operational costs, ISPs can manage their cash flow more effectively, freeing up capital for broader and faster network rollouts.
This revised financial approach is particularly beneficial for extending advanced fibre-optic networks and 5G connectivity into underserved regions, including many rural and semi-urban communities across the UK. Projects that once struggled to secure funding due to perceived low population density or high initial costs are now becoming viable. It is estimated that a significant proportion of households and businesses in areas with historically limited connectivity options stand to benefit from these expanded networks over the coming decade.
For end-users, this means accelerated access to gigabit-capable broadband and more reliable mobile services. While the direct impact on monthly pricing is subject to competitive market forces, the increased deployment and expanded capacity are expected to foster greater competition among providers, potentially leading to more diverse service offerings and improved value over time as infrastructure costs are amortised differently.
Addressing Potential Drawbacks
While the revised cost models present clear advantages in accelerating digital infrastructure expansion, serious objections have been raised regarding their long-term implications. Critics argue that the apparent reduction in initial outlay may mask deeper financial commitments and structural risks that could emerge over time.
There are concerns that these models, particularly those involving long-term service contracts or lease agreements, could lead to vendor lock-in, reducing an operator's flexibility to adapt to new technologies or switch providers without incurring substantial penalties. Furthermore, the total cost of ownership under an OpEx model, when viewed over the entire lifecycle of an asset, could potentially exceed a traditional CapEx approach, especially if service fees escalate or if the infrastructure requires extensive upgrades not covered by initial agreements.
The perceived cost reductions may merely defer significant financial obligations, potentially leading to higher long-term expenditure and reduced competitive agility for smaller market entrants.
Another area of concern is the potential for market concentration. Managing complex OpEx structures and long-term financial commitments often requires significant scale and sophisticated financial management, which might disproportionately favour larger, established infrastructure providers. This could inadvertently stifle competition from smaller, more agile entrants who may struggle to compete on the same financial terms, potentially leading to less innovation and choice in the market over time.
Uncertainty in Long-Term Sustainability
Long-Term Resilience and Innovation
A key unanswered question revolves around how these revised cost models will ultimately impact the long-term resilience and innovation capacity of the digital infrastructure sector. While they currently facilitate expansion, it remains to be seen whether a predominantly OpEx-driven environment will encourage or hinder the adoption of disruptive technologies and continuous improvement beyond initial deployments.
There is an ongoing debate about whether models focused on predictable, recurring revenues might favour maintenance and incremental upgrades over bolder, more speculative innovations that could fundamentally change network architecture. The ability of current financial agreements to adapt gracefully to unforeseen technological shifts, such as advancements in quantum computing or entirely new communication protocols, without requiring costly renegotiations or stifling progress, has not yet been fully tested at scale. The ultimate balance between investor returns, operational efficiency, and the imperative for future-proofing remains a critical area of observation.
Forthcoming Industry Signals
Several observable signals will indicate the ongoing trajectory and effectiveness of these revised cost models in the digital infrastructure sector. Major telecommunications companies and dedicated infrastructure funds are expected to release further announcements detailing expanded fibre rollouts, new data centre projects, and 5G mast deployments, explicitly referencing these new financial frameworks in their investment strategies.
Additionally, an increase in engagement from institutional investors, including pension funds and sovereign wealth funds, is anticipated as they seek to allocate more capital to dedicated digital infrastructure funds and greenfield projects. Government consultations and policy updates focusing on national broadband targets and digital connectivity strategies will likely continue, potentially adjusting regulatory incentives to further align with and support these evolving investment models. Industry analysts will also publish regular reports tracking the adoption rate of OpEx-heavy models, their impact on market share, and the profitability metrics among network operators, providing further insights into their efficacy.
Reader responses
Responses are read by the desk before they appear. A factual correction reaches us fastest here, and is made on the article itself with a dated note.
No responses on this report yet.